
Table of Contents
ToggleImportant Note & Disclaimer
Disclaimer: This article is provided for educational and informational purposes only and does not constitute financial, investment, tax, or legal advice. Mutual fund investments are subject to market risks. Investors should read all scheme-related documents carefully before investing. Past performance does not guarantee future returns. The calculations and examples used in this article are hypothetical illustrations intended only to explain how mutual funds and SIP investments work.
Introduction
If you are new to investing, understanding how mutual funds work with an example is the best way to clear your doubts and start your investment journey safely.
Many beginners always wonder about how mutual funds work with an example before putting their hard-earned money into the market.
Knowing how mutual funds work with an example helps you grasp financial concepts easily without confusion.
When people search online, they often look for clear guides on how mutual funds work with an example to make smart choices.
Every smart investor should study how mutual funds work with an example before opening a portfolio.
Knowing how mutual funds work with an example protects you from unnecessary financial risks.
Learning how mutual funds work with an example is essential for every beginner, and mastering how mutual funds work with an example gives you long-term confidence.
For someone who is new to investing, buying individual stocks can seem complicated because it requires research, monitoring, and an understanding of market movements.
Mutual funds offer another way to participate in financial markets. Instead of selecting individual securities yourself, you invest in a mutual fund scheme that pools money from many investors and invests it according to the scheme’s stated objective.
In this guide, we will thoroughly explore how mutual funds work with an example, covering SIPs, NAV, mutual fund units, diversification, fund managers, and the key factors beginners should consider before investing.
What Is A Mutual Fund?
A mutual fund is an investment vehicle that collects money from multiple investors and invests that pooled money in assets such as stocks, bonds, government securities, or other permitted securities, depending on the scheme.
Think of it like a group of people pooling their money to make a larger investment. When analyzing how mutual funds work with an example, this pooling mechanism is the very first step.
Every investor who wants to learn how mutual funds work with an example must first understand asset pooling.
- Example: Suppose 1,000 people each contribute ₹1,000. Together, they create a pool of ₹10 lakh. The mutual fund scheme then invests this money according to its investment objective.
- Each investor owns units of the mutual fund based on the amount invested and the applicable NAV.
- The value of these units can increase or decrease depending on the performance and value of the underlying investments.
How Do Mutual Funds Work? (Step-by-Step Guide)
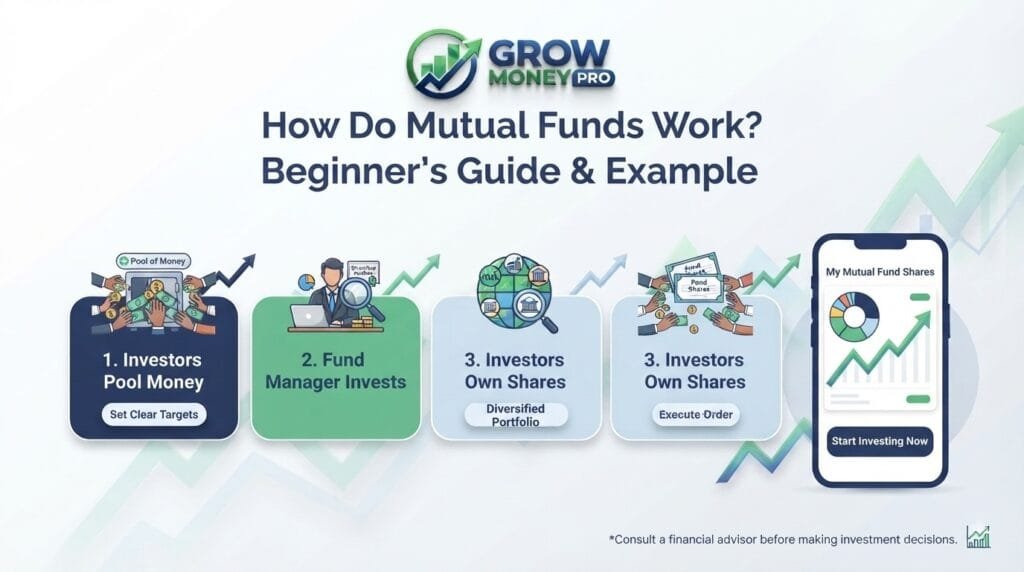
The basic process of how mutual funds operate can be understood in four simple steps:
1. Investors Pool Their Money
- Investors contribute money to a mutual fund scheme.
- The investment amount can vary, and beginners can start with relatively small amounts depending on the scheme.
- The money collected from investors forms a common investment pool.
2. The Asset Management Company (AMC) Manages the Scheme
- An Asset Management Company (AMC) manages mutual fund schemes and carries out various investment and operational activities.
- The AMC operates the schemes according to their stated objectives, applicable regulations, and investment mandates.
3. A Fund Manager Makes Investment Decisions
- A fund manager and the investment team analyze the securities and markets relevant to the particular scheme.
- Depending on the fund’s objective, they may select stocks, bonds, or other eligible securities.
- For example, an equity mutual fund may invest primarily in shares of companies, while a debt mutual fund may invest mainly in fixed-income securities.
4. The Money Is Diversified
- A mutual fund may invest across multiple securities and, depending on the scheme, different sectors or industries.
- An equity fund may hold companies from sectors such as Banking, IT, Pharmaceuticals, Automobiles, and Consumer Goods.
- Important: Diversification can help reduce the impact of poor performance by a single company or sector, but it cannot eliminate market risk or guarantee profits.
Ramesh’s Practical Example
Let’s understand the process with a simple hypothetical example tailored for Indian beginners who want to see how mutual funds work with an example in real life.
- Ramesh earns ₹30,000 per month. After managing his regular expenses and other financial commitments, he decides to invest ₹1,000 every month.
- Ramesh does not have the time or expertise to research individual stocks regularly. He therefore considers investing through a mutual fund SIP (Learn more about this in our guide on How to Start a SIP With ₹500).
- His ₹1,000 is combined with money from other investors in the selected mutual fund scheme, and the fund manager manages the scheme according to its objective.
- Over time, the value of the securities held by the fund may rise or fall, changing the value of Ramesh’s investment. This practical case study demonstrates clearly how mutual funds work with an example for everyday earners.
What Are Mutual Fund Units?
When you invest in a mutual fund, you do not directly receive shares of every company held by the fund. Instead, you receive mutual fund units. The number of units you receive depends on the amount you invest and the applicable NAV.
Simple Calculation Example:
- Suppose the applicable NAV of a mutual fund is ₹50.
- If Ramesh invests ₹1,000: \text{₹1,000} \div \text{₹50} = 20 \text{ units} (subject to applicable rules and charges).
- If the NAV later drops to ₹40 and Ramesh invests another ₹1,000: \text{₹1,000} \div \text{₹40} = 25 \text{ units}.
This shows how investing a fixed amount at different NAV levels can result in purchasing different numbers of units.
What Is NAV in Mutual Funds?
NAV stands for Net Asset Value. It represents the per-unit value of a mutual fund scheme, calculated based on the value of the scheme’s assets after accounting for applicable liabilities and expenses (Read a detailed breakdown at What Is NAV in Mutual Funds?).
- NAV changes as the value of the securities held by the mutual fund changes.
- A higher or lower NAV by itself does not determine whether a mutual fund is good or bad.
What Is SIP (Systematic Investment Plan)?
A SIP allows an investor to invest a fixed amount into a mutual fund scheme at regular intervals, such as monthly or quarterly.
- Instead of investing ₹12,000 at once, Ramesh invests ₹1,000 regularly throughout the year.
- SIP helps create a disciplined investment habit, but it does not guarantee profits or protect an investor from market losses.
Hypothetical SIP Investment Example
Let’s assume Ramesh invests using a SIP:
- Monthly SIP: ₹1,000
- Investment Period: 15 years (180 monthly investments)
- Total Amount Invested: ₹1,80,000
- Assumed Annual Return: 12% (Hypothetical illustration only)
| Financial Metric | Approximate Amount |
|---|---|
| Monthly SIP | ₹1,000 |
| Investment Period | 15 years |
| Total Amount Invested | ₹1,80,000 |
| Hypothetical Estimated Value | ₹5.05 lakh |
| Hypothetical Estimated Gain | ₹3.25 lakh |
Important: This is a mathematical illustration based on an assumed 12% annual return. Actual mutual fund returns can be significantly higher or lower, and the investment value can fall.
What Is Rupee Cost Averaging?
When an investor makes regular SIP investments, the same fixed amount buys more units when prices/NAV are low and fewer units when prices are high. This mechanism is known as rupee cost averaging (Explore more about how this works in Understanding Rupee Cost Averaging).
While it averages out your purchase cost over time, it does not guarantee a profit or prevent losses during a market downturn.
Important Factors to Check Before Investing
Before investing in any mutual fund, beginners should evaluate the following parameters:
- Investment Objective: Ensure the fund aligns with your goals (wealth creation, retirement, etc.).
- Risk Level: Check the scheme’s Riskometer to understand its underlying risk exposure.
- Expense Ratio: The annual fee charged for managing the scheme, which affects long-term net returns.
- Fund Category: Equity, debt, hybrid, or index funds.
- Investment Horizon: Match your expected timeline with the fund’s ideal holding period.
- Exit Load: Check if a fee applies for redeeming units early.
- Tax Implications: Understand capital gains tax rules applicable to your redemptions.
- Financial Goals & Risk Tolerance: Evaluate your overall financial situation and ability to handle short-term losses.
Direct Plans vs. Regular Plans
- Direct Plans: Purchased directly from the fund house without a distributor intermediary. They generally feature lower expense ratios because distributor commissions are excluded.
- Regular Plans: Purchased through brokers or distributors whose commissions are factored into the scheme’s higher expenses. (For a comprehensive comparison, check out our guide on the Difference Between Direct and Regular Mutual Funds).
Are Mutual Funds Safe?
Mutual funds are regulated investment products, but they are not risk-free. Because they are market-linked, returns are never guaranteed, and the value of your investment can rise or fall based on market performance and security prices.
Frequently Asked Questions (FAQ)
1. Can I start a mutual fund SIP with ₹500? Yes. Many schemes allow beginners to start SIPs with amounts as low as ₹500, though minimum requirements vary by scheme.
2. What is NAV in a mutual fund? NAV (Net Asset Value) is the per-unit price of a mutual fund scheme based on the total value of its assets minus liabilities.
3. How does SIP work? A Systematic Investment Plan (SIP) automatically invests a fixed amount at regular intervals into a chosen mutual fund scheme.
4. Are mutual fund returns guaranteed? No. Mutual fund returns are market-linked and unassured.
5. Can I withdraw money from a mutual fund? Yes, open-ended funds allow you to redeem units anytime, subject to exit loads, lock-in periods, and tax rules.
6. What is the difference between Direct and Regular mutual funds? Direct plans are bought without intermediaries and have lower expense ratios, whereas Regular plans involve distributor commissions.
7. Does SIP guarantee profit? No. SIP is only an investment method, and final values depend on market performance.
8. Can mutual funds lose money? Yes. Market-linked funds can decline in value if the underlying securities perform poorly.
Conclusion
Understanding how mutual funds work with an example helps clear up initial confusion for beginners. By pooling money, utilizing professional fund management, and employing disciplined strategies like SIP, investors can navigate financial markets systematically.
Always assess your risk tolerance, read scheme documents carefully, and align investments with your personal financial goals.
For official regulations, guidelines, and investor education resources, you can also refer to the Securities and Exchange Board of India (SEBI) and the Association of Mutual Funds in India (AMFI) portals.